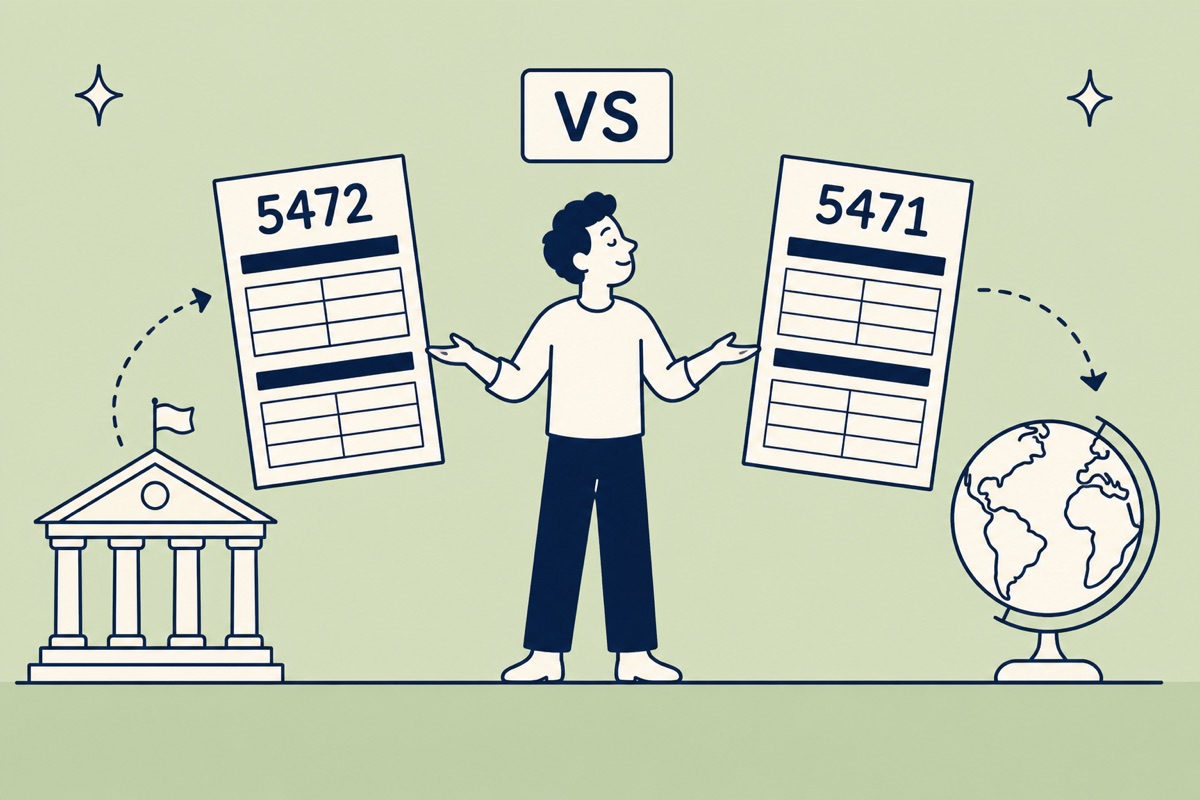
Form 5472 and Form 5471 share a numbering pattern and both live under the IRS’s international information-reporting rules, which is exactly why they get confused. In reality they report opposite ownership directions: one tracks a foreign person’s stake in a US entity, the other tracks a US person’s stake in a foreign one. Filing the wrong form, or assuming one covers the other, is how people end up with a $25,000 penalty for a form they never filed.
This guide lays out exactly which form applies to your situation, what happens when both apply at once, and how the penalties compare.
What Is Form 5472?
Form 5472 is an information return for a US corporation or US disregarded entity that is at least 25% foreign-owned. It reports reportable transactions (capital contributions, distributions, loans, service payments, and similar money movement) between the US entity and its foreign related parties. For the single-member foreign-owned LLC structure most non-resident founders use, Form 5472 is filed attached to a pro forma Form 1120. See the complete Form 5472 guide for the full picture.
In short: Form 5472 looks inward.It asks the IRS’s question “what is moving between this US entity and the foreign person or entity that owns it?”
What Is Form 5471?
Form 5471 (Information Return of U.S. Persons With Respect to Certain Foreign Corporations) is filed by US persons who are officers, directors, or shareholders in certain foreign corporations. Common triggers include a US citizen or resident owning 10% or more of a foreign corporation, acquiring or disposing of shares that cross ownership thresholds, or serving as an officer/director of a foreign corporation in which a US person holds a qualifying stake.
In short: Form 5471 looks outward.It asks the opposite question: “does a US person have an ownership interest in this foreign corporation, and what does that corporation’s financial picture look like?”
The Core Difference: Direction of Ownership
| Criteria | Form 5472 | Form 5471 |
|---|---|---|
| Direction | Foreign person owns a US entity | US person owns a foreign corporation |
| Who files | The US corporation or disregarded entity itself | The US person (individual or domestic entity) with the ownership interest |
| Ownership threshold | 25% or more foreign ownership of the US entity | 10% or more US-person ownership of the foreign corporation |
| What it reports | Reportable transactions between the US entity and its foreign related parties | The foreign corporation’s financials, ownership structure, and transactions with related parties |
| Attached to | Pro forma Form 1120 (for disregarded entities) | The US person’s own income tax return |
| Base penalty | $25,000 per form, per year | $10,000 per form, per year |
| Penalty cap | None — continuation penalties are uncapped | $60,000 per corporation, per year |
Who Must File Form 5472
You likely need to file Form 5472 if:
- You own a US single-member LLC that is treated as a disregarded entity, and a foreign person owns 25% or more of it (in practice, this means you as the sole foreign owner)
- You own a US corporation that is at least 25% foreign-owned
- Any money moved between you and the entity during the tax year, including a single capital contribution
Who Must File Form 5471
You likely need to file Form 5471 if:
- You are a US citizen or resident (a “US person”)
- You own 10% or more of a corporation formed outside the United States
- You are an officer or director of that foreign corporation and a US person holds a qualifying ownership stake in it
Note: most non-resident founders using Form5472.io do not personally file Form 5471, since Form 5471 is a US-person obligation and this form is triggered by owning a foreign corporation, not a US one. It becomes relevant mainly for US citizens or residents who separately hold foreign company stakes.
Can You Owe Both Forms?
Yes, though the scenario is specific. A US person who both (a) owns 10%+ of a foreign corporation and (b) is a related party to a foreign-owned US LLC or corporation can trigger both filings in the same year, one for each direction of ownership. A common real-world example: a US citizen who owns a foreign holding company (Form 5471) while also being a related party in transactions with a foreign-owned US LLC (Form 5472 for that LLC). The two filings are independent, each with its own form, deadline, and penalty exposure.
Need to file Form 5472 for your foreign-owned LLC? Form5472.io generates your Form 5472 and pro forma 1120 in about 15 minutes, IRS-ready. Form 5471 is a separate, more complex filing best handled by a CPA familiar with controlled foreign corporation rules.
File your Form 5472 →Penalty Comparison: Why the Gap Matters
Form 5472’s penalty structure is materially more dangerous over time. Form 5471 starts at $10,000 and tops out at $60,000 per corporation per year, even with continuation penalties. Form 5472 starts at $25,000 and has no statutory ceiling: if the IRS mails a notice and 90 days pass without a response, an additional $25,000 is added for every 30-day period the failure continues, indefinitely. Missing several years of Form 5472 for a single LLC can realistically exceed what a Form 5471 failure would ever cost.
Neither form carries a reasonable cause exception written into the statute, though the IRS does accept reasonable cause abatement requests after the fact for both.
Key Takeaways
- Form 5472reports a foreign person’s ownership of a US entity. Form 5471reports a US person’s ownership of a foreign corporation. They track opposite directions.
- Most foreign-owned single-member LLCs only need Form 5472, not Form 5471.
- A US person can owe both in the same year if they separately own a foreign corporation and are a related party to a foreign-owned US entity.
- Form 5472’s penalty is uncapped over time; Form 5471’s caps at $60,000 per corporation per year.
- Neither form substitutes for the other — evaluate each filing requirement independently.
Frequently Asked Questions
Can one person need to file both Form 5472 and Form 5471?
Yes. If a US citizen or resident owns 10% or more of a foreign corporation, and that same person’s foreign-owned US LLC has reportable transactions, two entirely separate filings are required: Form 5471 for the foreign corporation and Form 5472 (with a pro forma Form 1120) for the US LLC. Neither form substitutes for the other.
Is Form 5471 only for foreign corporations, not foreign LLCs?
Form 5471 applies to foreign corporations. A foreign LLC that elects to be treated as a corporation for US tax purposes can trigger a Form 5471 filing requirement for its US owner. A foreign LLC that is treated as a partnership or disregarded entity does not trigger Form 5471; different forms (such as Form 8865 for foreign partnerships) may apply instead.
Which form has the bigger penalty?
Form 5472’s $25,000 penalty has no statutory cap: it keeps adding $25,000 for every 30-day period after a 90-day IRS notice, indefinitely. Form 5471 starts lower, at $10,000 per form, but is capped at $60,000 per corporation per year (base penalty plus continuation penalties). Per-instance, Form 5472 is more expensive and riskier over time.
I’m a foreign national who owns both a US LLC and a foreign company. Do I file either form?
Form 5471 is a US-person filing: it applies to US citizens, residents, and certain domestic entities with an interest in a foreign corporation. A foreign national who is not a US person generally does not file Form 5471 for a foreign company they own. Their US LLC’s Form 5472 obligation is unaffected by this and still applies if the LLC is foreign-owned.
Does filing Form 5472 mean I do not need to worry about Form 5471?
The two forms answer different questions and neither one covers the other. Filing Form 5472 satisfies only the foreign-owned-US-entity reporting requirement. If you separately have an ownership interest in a foreign corporation as a US person, you still need to evaluate the Form 5471 requirement on its own.
File Your Form 5472 in Minutes
Skip the paperwork. Our digital tool generates IRS-ready Form 5472 and Pro Forma 1120 instantly.
Start Filing Now